Scene 1 (0s)
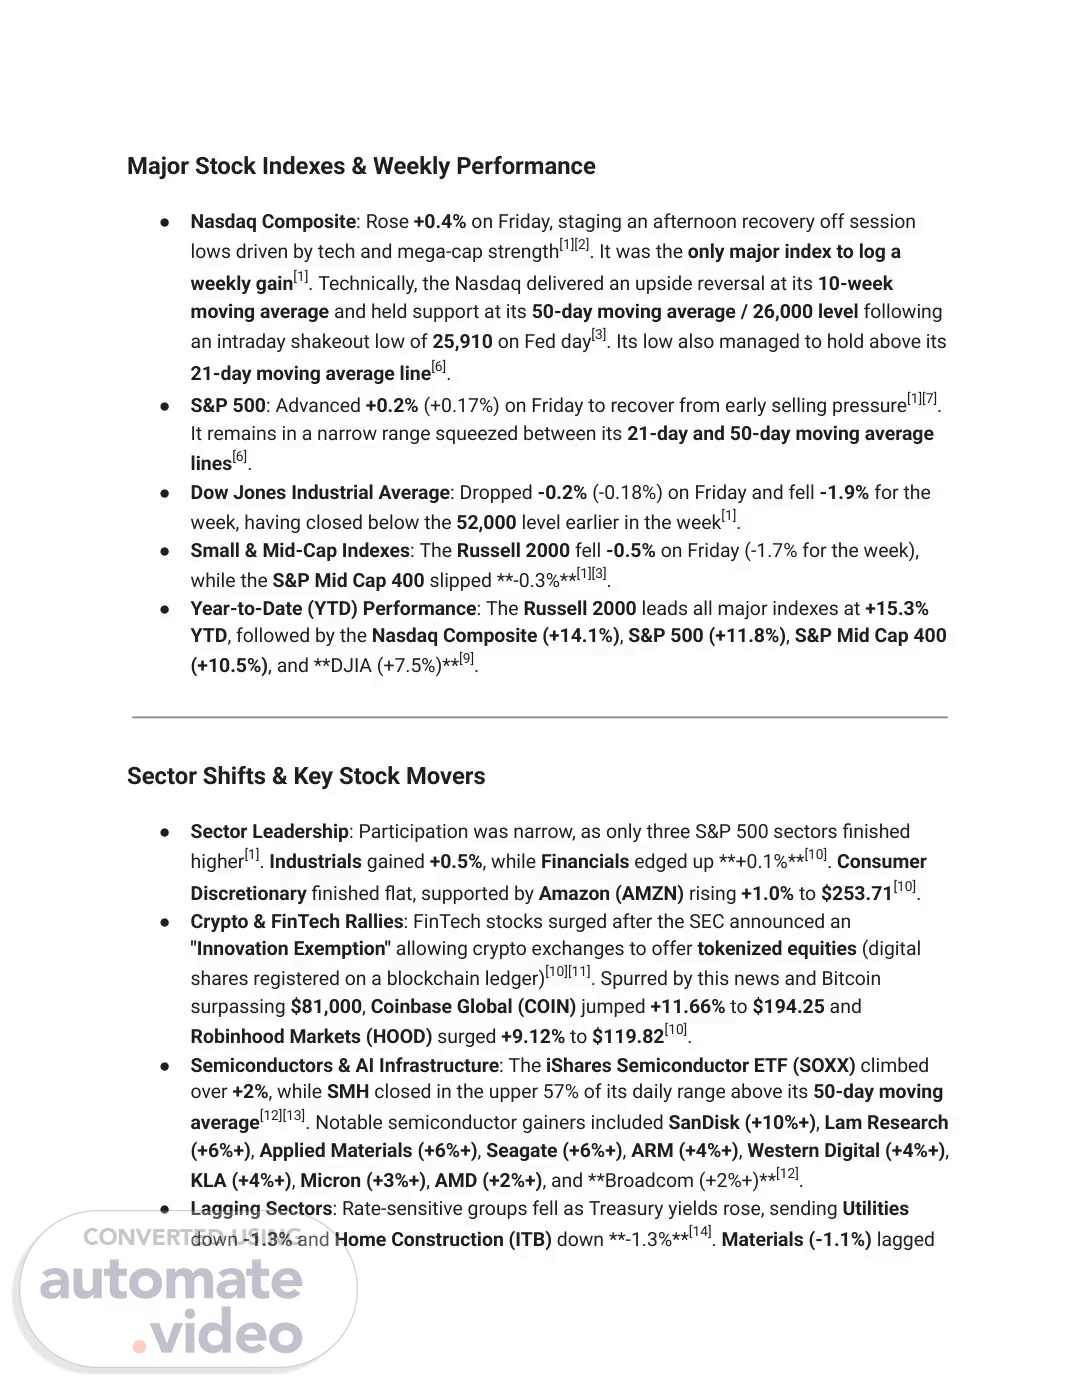
[Audio] Major Stock Indexes & Weekly Performance Nasdaq Composite: Rose +0.4% on Friday, staging an afternoon recovery off session lows driven by tech and mega-cap strength[1][2]. It was the only major index to log a weekly gain[1]. Technically, the Nasdaq delivered an upside reversal at its 10-week moving average and held support at its 50-day moving average / 26,000 level following an intraday shakeout low of 25,910 on Fed day[3]. Its low also managed to hold above its 21-day moving average line[6]. S&P 500: Advanced +0.2% (+0.17%) on Friday to recover from early selling pressure[1][7]. It remains in a narrow range squeezed between its 21-day and 50-day moving average lines[6]. Dow Jones Industrial Average: Dropped -0.2% (-0.18%) on Friday and fell -1.9% for the week, having closed below the 52,000 level earlier in the week[1]. Small & Mid-Cap Indexes: The Russell 2000 fell -0.5% on Friday (-1.7% for the week), while the S&P Mid Cap 400 slipped **-0.3%**[1][3]. Year-to-Date (YTD) Performance: The Russell 2000 leads all major indexes at +15.3% YTD, followed by the Nasdaq Composite (+14.1%), S&P 500 (+11.8%), S&P Mid Cap 400 (+10.5%), and **DJIA (+7.5%)**[9]. Sector Shifts & Key Stock Movers Sector Leadership: Participation was narrow, as only three S&P 500 sectors finished higher[1]. Industrials gained +0.5%, while Financials edged up **+0.1%**[10]. Consumer Discretionary finished flat, supported by Amazon (AMZN) rising +1.0% to $253.71[10]. Crypto & FinTech Rallies: FinTech stocks surged after the SEC announced an "Innovation Exemption" allowing crypto exchanges to offer tokenized equities (digital shares registered on a blockchain ledger)[10][11]. Spurred by this news and Bitcoin surpassing $81,000, Coinbase Global (COIN) jumped +11.66% to $194.25 and Robinhood Markets (HOOD) surged +9.12% to $119.82[10]. Semiconductors & AI Infrastructure: The iShares Semiconductor ETF (SOXX) climbed over +2%, while SMH closed in the upper 57% of its daily range above its 50-day moving average[12][13]. Notable semiconductor gainers included SanDisk (+10%+), Lam Research (+6%+), Applied Materials (+6%+), Seagate (+6%+), ARM (+4%+), Western Digital (+4%+), KLA (+4%+), Micron (+3%+), AMD (+2%+), and **Broadcom (+2%+)**[12]. Lagging Sectors: Rate-sensitive groups fell as Treasury yields rose, sending Utilities down -1.3% and Home Construction (ITB) down **-1.3%**[14]. Materials (-1.1%) lagged.
Scene 2 (4m 28s)
[Audio] due to Q3 earnings guidance cuts from steelmakers Nucor (-6.32% to $248.38) and **Steel Dynamics (-4.11% to $235.26)**[14][15]. Communication Services (-0.7%) was dragged down by Netflix (-4.70% to $71.77) following a Wells Fargo downgrade to Underweight[2][15]. Treasuries, Macro Data & Commodities Treasury Yields: Yields rose across shorter and benchmark tenors, locking in weekly losses for Treasuries[9]. The 10-year Treasury yield rose 5 bps (to 4.996% / 5.00%), up 2 bps for the week, driven by negative carryover from the Fed's 25 bp rate hike, hawkish signaling, and comments from Kansas City Fed President Jeff Schmid[9]. The 2-year Treasury yield gained 5 bps to 4.74% (+10 bps for the week)[9]. Futures markets currently price in a 55% chance of a +25 bp Fed rate hike at the Oct 27–28 FOMC meeting[16]. Economic Data: August Industrial Production was unchanged m/m (below the 0.3% consensus) with capacity utilization at 76.3%, reflecting softness in manufacturing output[17]. The August Leading Economic Index (LEI) fell -0.1% (versus +0.2% expected)[17]. Commodities: WTI Crude Oil fell -1.8% (over -1%) to settle at $100.24 per barrel, ending nearly flat for the week[2][18]. Oil weakness was aided by Middle East diplomatic efforts and reports that 18 million barrels passed through the Strait of Hormuz on Tuesday[18]. Actionable Insights & Technical Setups for Next Week Nasdaq Composite: Look for follow-up buying strength early next week to clear the current sideways trading range[5][19]. Holding above the 50-day moving average / 26,000 level will be crucial after the recent Fed day shakeout[4][5]. S&P 500: To confirm a sustainable bounce, look for the daily low (not just the close) to get above the 21-day moving average line[6][20]. Pullbacks testing the 50-day line can present entry opportunities if support holds[20]. Semiconductors (SMH / SOXX): The primary test for SMH next week is to stay above its 50-day moving average rather than suffering another rejection[13]. Because chip stocks carry roughly twice the weight of software in tech benchmarks, sustained semiconductor strength is necessary to power broader tech gains[21]..
Scene 3 (7m 48s)
[Audio] Tech Sector ETF (XLK): Has broken its primary downtrend line and is coming up to test horizontal resistance[22]. High-Yield Credit (JNK): Monitor junk bond prices and yields as a leading market indicator; rising JNK prices and falling yields indicate lower corporate borrowing costs and historically signal a green light for equity market rallies[23]. Robinhood Markets (HOOD): Found strong support at its 50-day moving average line, setting up a second-chance entry opportunity following its recent pullback[24]. e.l.f. Beauty (ELF): Rebounded +3.3% as it tests support at its rising 10-week moving average line following a cup-with-handle breakout[25]. Targa Resources (TRGP): Showing tight consolidation while holding above its 10-week moving average line with its Relative Strength (RS) line in an uptrend[26]. ARK Innovation Funds: Late-week outperformance in ARCG (genomics infrastructure) and ARCW (next-gen internet and crypto) points to.